Choosing a Structural Steel Supplier When the Building Is Insured
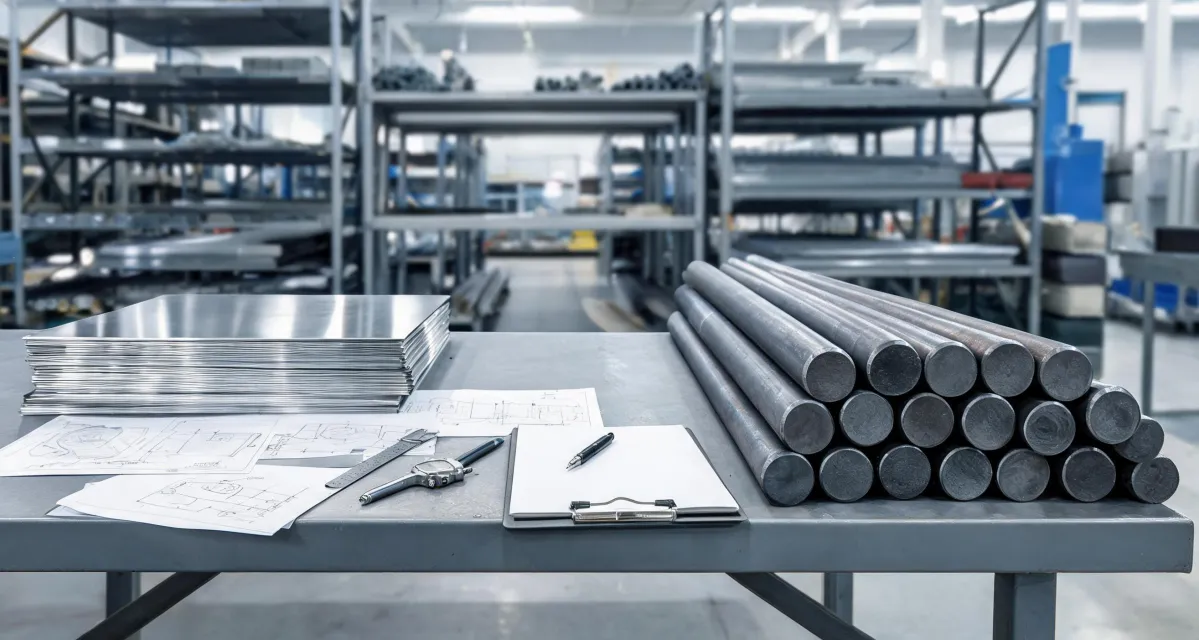
A structural steel purchase for an insured building starts as a price decision and often stays that way until a claim form is opened. Imagine two supplier quotes on the same table. The first lists the metal as a simple one-word description, promises a fast delivery date, and undercuts the other by a noticeable margin. The second names an alloy, a temper, and a compliance reference, and supports the metal with a document trail. On a tight site budget, the first quote looks responsible, because no one wants to spend extra on paperwork when the roof still has to go on. That instinct is the one to challenge. Insurance underwriting and claim review treat material traceability as part of the risk, and a frame assembled from unidentifiable material cannot be defended even if it performs well. The supplier decision is therefore a decision about what can be proven years after installation, not only about what can be built today.
The Insurance Lens No One Mentions Until a Claim Arrives
The practical question is not which shop delivers the cheapest tonnage; it is which quote tells a complete story about the metal itself. Two offers for the same structural task can look almost identical until the second page arrives. One page names an alloy and a temper and gives the thickness tolerance. The other page simply says steel plate and stops. The lower-cost option is tempting because the construction budget is finite and the inspector has not arrived yet. But a buyer who cannot name the alloy also cannot name how the material will behave in a brake press, in a weld, or along the corrosion line. The fabricator may not raise the issue, because the job is small and the margin is thin. That leaves the risk with the homeowner or the builder, who needs a vocabulary that goes beyond pounds, delivery dates, and quote totals.
Once the insurance dimension is added, that vocabulary becomes easier to justify. An insurer watches the finished asset, not the fabrication process, and it investigates when a claim arrives. A strong engineering drawing and a clean weld are not enough if the structural material itself lacks identification. When an adjuster asks what carries the load at a damaged corner, the answer has to be a grade, a temper, and a compliance reference, not an invoice line that says steel. The same discipline that protects the building also protects the policyholder’s right to a covered repair. That is why the purchase shifts from price bidding to risk matching: the buyer is asking whether the metal is identifiable, appropriate to its job, and documented well enough to survive a second look later. A documented material is also easier to maintain, replace, and match in a later repair, and those tasks become part of the insurance record too.
Read the Quote: Grade and Temper Before Price
Start with the first page of a competent quote, and the next question is what the alloy designations actually mean. Do not begin with the price column. Begin with the four-digit alloy number and the hyphenated temper that follow it, because those two pieces of shorthand describe what the material is supposed to do. A quote that omits them removes the only public language a buyer can use to compare one offer with another. Without that language, every ton of aluminum or steel looks interchangeable, and the buying decision collapses into whichever vendor returns a phone call. The point of the next few minutes is to make grade and temper legible, so that a price difference is judged after the material specification, not before it. It is the part of the process that separates a metal supplier with real technical knowledge from a broker who simply moves inventory.
The pattern behind those designations assigns a duty to each material. A detailed decision guide groups 5052 under marine, forming, and enclosures; 6061 under structural, CNC, and aerospace work; and 7075 under defense, high-load, and research roles. Translated into building terms, 5052 offers the corrosion resistance and formability that suit salt air and bent panels, 6061 offers the strength and machineability that ordinary structural framing needs, and 7075 is reserved for applications under extreme load. The same guide explains that aluminum grades follow the Aluminum Association standard compositional system, so the alloy number is public, published information rather than a supplier’s private label. That fact changes the judgment: matching the quote to the building becomes a matter of checking whether the named grade fits the duty the part will carry. When a quote skips the alloy number, the supplier is already signaling that it sells metal by weight, not by application. The cheapest slab of aluminum can become a serious mismatch when the building requires a structural grade, which is exactly the mismatch an insurer will notice later.
Temper is the half of the specification that gets skipped, yet it governs behavior during fabrication as much as the alloy does. H14, H32, and T6 are not decorative suffixes; they tell a fabricator how much mechanical or thermal treatment the metal has received and how it will respond to bending, machining, and welding. Fabrication guidance is blunt on this point: the wrong temper can cause cracking during bending, excessive springback, poor finish, or needless difficulty in the shop. When a structural part is formed from a coil or a flat sheet, a wrong temper can convert a one-day job into a week of scrap and rework. The evidence matters because it moves the conversation from what the alloy contains to what has been done to it. A quote that names 6061 without a temper leaves out the variable the fabricator feels first. The rule that follows is short: grade names the duty, temper names the behavior, and a complete purchase order carries both.
Where It Sits Decides How It Ages
Before any price is signed, a location question has to be answered: where will the steel actually sit? A structural member in a dry interior carries a different environmental load from one exposed to road splash, coastal fog, or salt air, and that difference affects both alloy choice and supplier expectation. The technical case for aluminum in exposed settings rests on documented behavior rather than vague assurances. Aluminum is a light metal, roughly one third of the density of steel, copper, and brass, and it offers good corrosion resistance in common atmospheric and marine exposures; anodizing adds another layer of corrosion and scratch protection. These details are not decoration. They tell a homeowner near the coast that unprotected steel may age differently from a corrosion-resistant aluminum section, and they tell a designer that the protective behavior of the material was considered before the frame was ordered. When a quote leads with a marine-capable alloy or a data sheet that notes outdoor service, the supplier is matching the metal to the site. When the quote is silent on the subject, the exposure question is simply postponed until a claim makes it unavoidable. That silence is itself information, because exposure is predictable, durable, and visible in the claim file.
Once exposure is on the table, corrosion becomes a life-cycle cost rather than a finish detail. The rust that stains a panel is usually the last step in a chain that began with a scratch, trapped moisture, or contact between two different metals. What happens to a structural connection under that kind of attack is not resolved by painting over it; the outcome depends on whether the material was selected to tolerate the environment from the start. Aluminum’s protective oxide layer is part of the reason the metal performs in atmospheric and marine settings, but the same logic does not automatically cover every bracket, fastener, or contact point in the building. Those small parts carry their own corrosion behavior, and a supplier who treats them as part of a coherent corrosion plan gives the buyer more than a roof frame; it gives the whole structure a serviceable future. The takeaway is not exotic. It asks whether the proposal treats the site as an environmental input and whether the metal will look as sound in year twelve as it did on the day it was delivered. The most useful corrosion specification is the one written down, because it gives an inspector a baseline against which later damage can be measured.
The Paper Trail That Makes a Supplier Credible
With the duty and the site understood, the next question moves from the metal to the folder: what documentation actually proves what the supplier claims? A sourcing guide written for aluminum buyers is a useful mirror here, because it puts alloy, temper, strength-to-weight ratio, and corrosion resistance at the center of the purchasing decision. If a supplier cannot present those same categories in writing, the verbal assurance is hollow. The question to put to any vendor is practical: will you state the grade, the temper, and the compliance reference on the order? A salesperson who knows the material answers without hesitation; one who is moving coil by price will search for an exit. The guide makes the deeper point that sourcing is a multi-variable decision, and the document is what lets a buyer compare those variables across vendors. The absence of that answer is reason enough to slow down the purchase, because documentation is cheaper to obtain before money changes hands than after.
When a supplier is willing to document, the useful page looks more like an engineering table than a sales invoice. A data sheet for 3003-H14 flat sheet, for example, includes an ASTM B209 compliance note, a nominal thickness of 1.0 mm or 0.040 in, standard widths of 48.0 in or 1,220 mm, and a thickness tolerance of plus or minus 0.004 in or 0.10 mm. Its chemical composition table then lists manganese and silicon against their standard ranges. That level of detail converts a sourcing conversation into a checklist. The buyer can confirm that the alloy fits the intended part, the temper fits the forming process, and the standard reference matches a published specification. The same industrial guide describes thin flat sheet in thicknesses from 0.2 mm to 6.0 mm, a useful reminder that material form and processing range are part of the very same technical story. What makes this evidence valuable is its role in a future dispute: a data sheet can be filed beside a mill certificate and pulled out if a claim asks for proof of what was installed. A supplier who will not produce that page is not failing on price; it is failing on verifiability, and verifiability is the variable an insurer will actually care about.
The Decision Rule for an Insured Build
The outline of a defensible purchase is now clear: choose a grade that matches the structural role, add a temper that matches the fabrication process, account for the environmental exposure of the site, and demand the documents that make all three visible to an inspector. Notice what is missing from the list: the lowest price. Cost has not disappeared; it has moved to the end of the queue. That reversal is not a luxury; it is simply what an insured structure requires. A home rebuilt with a documented aluminum alloy, a sensible temper, and a data sheet naming the standard has a stronger story in an insurance review than the same frame bought at a discount with no technical history. The adjuster’s question is never what the material cost; it is always what the material is. The decision rule below is written to be reused on the next project, not memorized for this one.
The final rule fits on a single line: when suppliers compete for structural steel on an insured building, choose the one that produces grade, temper, and compliance documentation in a consistent format, and treat a quote that keys only to price as a failed applicant. Use that rule as a gate before asking about delivery schedules or labor rates. If the supplier cannot name the alloy and temper on the order form, the material is an insurance liability no matter how inexpensive it is; if the supplier can name them but offers no compliance reference, it is asking the buyer to accept a risk that belongs in an engineering review. Repeat the same question with every vendor: can the metal be identified and matched to a specification? For a covered rebuild, that is not paperwork for its own sake. It is the difference between a claim that settles cleanly and one that opens with a material investigation.
When a price quote cannot name the grade, the temper, and the written compliance reference, that quote fails before the cost is read. The supplier who lays out all three in a consistent format is the one whose material can be verified on paper, and verifiability is the only reason an insurer can treat the structure as an asset rather than an unknown.
Ingrid Solberg
Ingrid Solberg is an independent carbon and structural steel analyst covering steel plate, sheet, coil, pipe, beams, rebar, and galvanized products. She applies ASTM A36/A36M and A6/A6M requirements while comparing grade chemistry, yield strength, tensile strength, elongation, dimensional tolerance, weldability, and surface condition. Her evidence-led guides help engineers, fabricators, and procurement teams select suitable steel forms, define purchase specifications, and evaluate mill or service-center offers.