Choosing a Structural Steel Supplier When Home Insurance Is Paying for the Rebuild
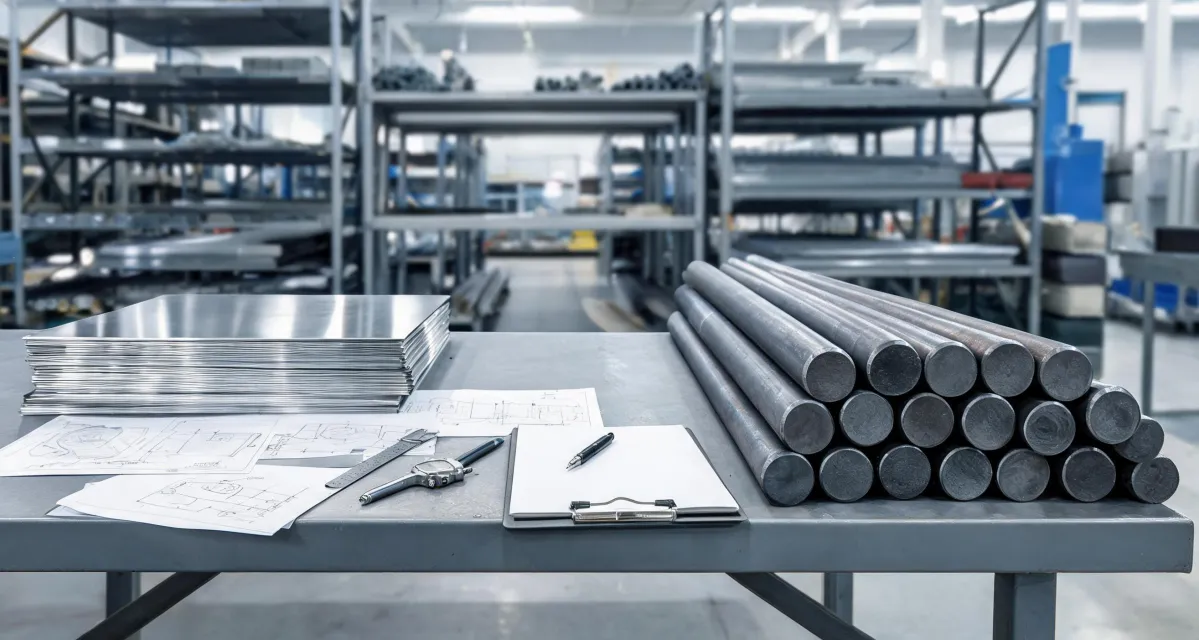
You are holding two structural steel quotes for the same load-bearing wall, and they are not close in price. Supplier A offers a lower per-pound rate and promises 'structural steel, ready to ship.' Supplier B charges more but attaches alloy designations, mechanical property limits, and standard-compliance sheets. In a home insurance-backed rebuild, the cheaper quote can become the expensive mistake: if the material certificate does not match the engineering spec, the claim can be rejected and the wall may have to be replaced. The right structural steel supplier is the one whose material certification is auditable before price is compared, because that documentation protects both the claim and the structure.
Two Structural Steel Quotes: Which One Protects Your Home Insurance Claim?
Which of these two quotes should a homeowner trust with a load-bearing repair? The first is a barebones price per pound; the second includes alloy designations, temper or grade, and a note about ASTM compliance. The cheaper one may seem sensible, but instinct ignores what happens after material arrives. If the installed steel cannot be traced to a documented standard, the repair may fail inspection or be excluded from the claim. The question is not about liking one salesperson more; it is about which quote can survive the documentation check that insurance and building approval require. That check begins before price negotiation, not after the steel is cut. This article walks through the criteria that separate a quote you can approve from one that turns an approved repair into a rejected claim.
Supplier comparison guides for metal components use exactly this standard. A sourcing guide for aluminum sheet put together by an engineering supply company warns that a quote that simply says 'aluminum sheet' is not comparable to one that names 5052-H32 or 6061-T6. The same principle applies to structural steel: a grade designation and a processing condition give you something to verify, while a generic label gives you nothing. When a claims adjuster or building official reviews the repair, they will ask what material was installed and whether it meets the spec. The supplier who can answer that question with a document shifts the risk away from the homeowner; the supplier who cannot leaves the risk on the structure. The guide's total-cost logic also shows why the low quote is deceptive: if the material lacks documented properties, rework, inspection delays, and potential claim denial add costs that dwarf the price difference. In short, the first filter is not the price per pound; it is whether the quote can be matched to an auditable material identity.
A common misconception is that any certified structural metal is interchangeable as long as the label says 'steel' or 'aluminum.' A temper guide for aluminum explains why that is wrong: the same alloy in H14, H32, or T6 behaves differently in bending, springback, and load capacity. The wrong temper can crack during forming or fail in service, even when the alloy number is identical. For steel, the equivalent distinction shows up in grade and condition—a higher-strength grade is not automatically better if the fabricator's process assumes a different material. The mistake is treating documentation as paperwork instead of as a description of how the metal will perform. This simple correction changes the entire conversation with a supplier. Once a homeowner understands that the temper or grade is part of the structural design, the first question to a supplier stops being 'what is your price?' and becomes 'what exactly is this material, and can you prove it?'
Start with Alloy and Temper, Not the Price Tag
Before comparing prices, which two material specifications should a homeowner ask for? The answer is the grade and the temper—or for steel, the grade and the processing condition. These two details determine whether the metal can carry the load, form without cracking, and hold up in service. A certified supplier will usually put them on the quote; a supplier who avoids naming them is hiding the information you need for the insurance file. The grade tells you the alloy family; the temper tells you how the metal was worked and what mechanical properties to expect. That is the first checklist item when you open a quote. It is the single question that prevents a mismatch later.
The point is explicit in alloy selection guides. A guide to choosing aluminum sheet explains that the alloy number plus the temper designation is the first thing to review, because 3003, 5052, and 6061 each have different strength, corrosion resistance, and workability. A separate temper guide goes further, showing that H14, H32, and T6 tempers can make the same alloy behave differently in the shop and in service. The implication for structural steel is direct: the grade name alone is not enough; the mechanical property limits are what connect the material to the engineering spec. When a supplier lists 'ASTM B209, 3003-H14' on a data sheet, they are giving you a verifiable baseline. The structural steel equivalent would be a grade plus a standard reference and property limits, not just a marketing name. That is the level of specificity an insurance adjuster and a building official expect. Ask for the mill certificate or test report that states yield strength, tensile strength, and any required ductility values. If a supplier cannot produce those, the quote is incomplete. This is not a formality; it is how you confirm that the purchased material can actually carry the load.
A technical data sheet for 3003-H14 aluminum flat sheet shows what this documentation looks like in practice: standard thickness, width, length, production tolerances, chemical composition ranges, and mechanical property limits such as tensile strength, all tied to ASTM B209. The sheet makes it possible to check whether the delivered material matches the ordered spec. For structural steel, the same logic applies: you want the supplier to give you a data sheet that names the grade, the standard, the property limits, and the tolerances. The contrast between a supplier who can produce this and one who cannot is the difference between a building component you can approve and a component you are betting on. And because the data sheet is part of the audit trail, it is also the document an adjuster will ask for if the claim is reviewed. Without that document, your only evidence is a verbal promise, and a verbal promise never satisfied an insurance auditor. So when a supplier offers to email the cert later, ask for it in the quote instead.
Certification and Documentation: The Insurance Layer
Why does material documentation become part of an insurance claim? Because an adjuster does not evaluate a repaired wall by looking at it; they evaluate it by the records that prove it was rebuilt to code. A mill certificate, a test report, and a standard-compliance statement connect the installed steel to the approved engineering design. Without those records, the repair is essentially unverifiable, and an unverifiable repair is a risk the policy may not cover. The documentation is not extra bureaucracy; it is the evidence that the material is what the engineer specified. This is why a supplier who treats paperwork as optional is a red flag for an insurance-backed project. When a storm-damaged home is rebuilt, the local building department and the insurer share the same question: can you prove that the load-bearing members meet the approved spec? Documentation answers it.
Risk-control playbooks outside construction make the same audit principle explicit. A supplier verification guide for coated kitchen knives, which sounds unrelated, spends most of its pages on how to verify authenticity, document coating safety, and build recertification workflows, because missing paperwork can trigger inspections, product recalls, and liability. The logic transfers directly to structural steel: a supplier's certification and compliance documents are part of risk control, not a courtesy. A data sheet like the 3003-H14 example anchors this by showing exactly what an auditable record contains—alloy, standard, composition, and mechanical limits. For a home insurance claim, the audit trail is what converts an approved repair into a paid claim. If the steel lacks a test report, an adjuster can question whether the material meets code, and the homeowner can be stuck with the cost of proving it. The practical step is to ask for the mill test report before you order, not after delivery. A supplier who cannot provide it is asking you to take on a risk that the insurance company and building department will not take. Consider that an uninsured verification cost is still a cost.
The judgment call for a homeowner is simple: treat missing documentation as a dealbreaker. A supplier who says 'we have the certs in the office' but cannot attach them to the quote may still be honest, but the risk is not worth the lower price. If the material arrives without the required records, the project stops at inspection, and the insurance claim can be delayed or denied. The only way to protect the project is to make the documentation part of the purchase order, with the standard and property limits written into the order. That way, if the paperwork does not show up, the problem is the supplier's, not yours. Make that expectation clear in the request for quote, so there is no ambiguity later. And if a supplier pushes back, treat that reaction as information: the structural steel supply chain is full of companies that issue mill certs routinely, so resistance usually means the material cannot be traced.
Compare Total Cost, Not Just Price per Pound
When two certified suppliers both provide the right documentation, what is the real difference in cost? The per-pound price is only the starting point. The full cost includes processing, lead time, delivery reliability, and the risk of a rejected claim. A supplier who is cheaper per pound but slower can cost more in delay and rework. The question to ask is not 'what do you charge?' but 'what does the complete purchase cost after installation and inspection?' A documented quote lets the buyer compare apples to apples; a bare price hides the final bill. For insurance-backed work, the cost of a claim denial can exceed the entire material bill, so total cost must include that risk. This is the real number to compare.
The guide used earlier for grade selection also applies total-cost logic. It points out that the cheapest per-kilogram quote is often the most expensive once you add rework, delivery problems, and the cost of a failed inspection. The same is true for structural steel: a supplier who cannot hold a tight tolerance or deliver a cert on time can delay a rebuild that depends on weather, labor, and insurance deadlines. A slightly higher per-pound price from a supplier with documented processing capability and a clean audit trail is usually the lower total cost. The guide's practical advice is to ask for a complete quote that itemizes material, processing, certification, and lead time, then compare those totals rather than the unit price. This method turns a vague comparison into a decision you can defend if the adjuster questions the choice. It also gives the contractor a paper trail that shows due diligence in selecting a conforming supplier. And when the final invoice arrives, there are no surprises hiding in the processing line. This is the difference between a quote and a quote you can actually approve.
The practical application shows up in product form selection. A guide to aluminum sheet, plate, and coil explains that the same alloy is available in different forms and thicknesses, from thin sheet to heavy plate, and the form affects processing and cost. For structural steel, the equivalent is choosing between beam, channel, plate, and custom fabrication, each with different labor and lead time. A supplier that stocks the right product form and offers cutting or shearing in-house is worth more than one that only brokers material, because fewer handoffs mean fewer chances for documentation to get lost. The supplier with a broader service range often beats the low price on material alone. That is why the application step is not about metallurgy; it is about whether the supplier can deliver the material in the form the engineer specified, with the paperwork attached. Ask your supplier for a cut-to-size quote with the certification pack included, and you will see the difference immediately.
A Reusable Rule for Choosing a Structural Steel Supplier
After comparing quotes, can a homeowner boil all this down to one reusable rule? Yes: first verify, then price. Before any conversation about dollars, ask for the grade, the temper or condition, the applicable standard, and the mechanical property limits. If the supplier provides them in writing, move to price. If they hesitate, walk away. That one rule protects the claim and the structure. It applies whether the project is a repair or a new build and whether the material is structural steel or another metal. Make it a standard line in every request for quote: 'All quotes must include material grade, condition, standard compliance, and mechanical test reports before pricing is reviewed.'
The same sourcing guide that used the verify-then-price structure shows why this order matters. When it walks through supplier comparison, it does not start with cost; it starts with whether the quote names a specific alloy and temper. Only after that does it move to total cost analysis. That sequence is the rule in action: certification and mechanical specs are the filter; price is the final step. For a home insurance build, the filter matters twice because the insurance company and the building department both use the same documents to judge the repair. A supplier who cannot pass the first filter is ineligible no matter how competitive the price. The rule also saves time, because it eliminates quotes that will never survive review. It also gives the contractor a defensible reason for choosing a higher-priced supplier if a claim is audited. The documentation becomes evidence of due diligence, not a bunch of papers. In practice, this means a two-step process: shortlist by material identity, then choose by total cost. This is the difference between buying a product and buying an insured, code-compliant component.
The material comparison in a technical manual for aluminum reinforces why the rule has substance: aluminum weighs one third as much as steel, yet some alloys match or exceed the strength of common construction steel. That does not mean aluminum is always the right choice; material choice has to be made by load, environment, and cost. The same discipline applies within structural steel: different grades are chosen for strength, weldability, and corrosion resistance, and the supplier who can explain why a grade fits the loading case is the one to trust. The rule holds: verify grade, condition, standard, and properties first; compare total cost second; treat any supplier who cannot document these as disqualified. This is not a preference.
So when the two quotes come in, the cheaper one is not automatically wrong, but it must pass the documentation test before it earns a second look. The reusable rule is very simple: verify first, price second, and that rule keeps a rebuild both standing and covered.
Ingrid Solberg
Ingrid Solberg is an independent carbon and structural steel analyst covering steel plate, sheet, coil, pipe, beams, rebar, and galvanized products. She applies ASTM A36/A36M and A6/A6M requirements while comparing grade chemistry, yield strength, tensile strength, elongation, dimensional tolerance, weldability, and surface condition. Her evidence-led guides help engineers, fabricators, and procurement teams select suitable steel forms, define purchase specifications, and evaluate mill or service-center offers.