Certified Structural Steel Beams vs. Cheap Quotes: What Home Insurers Price
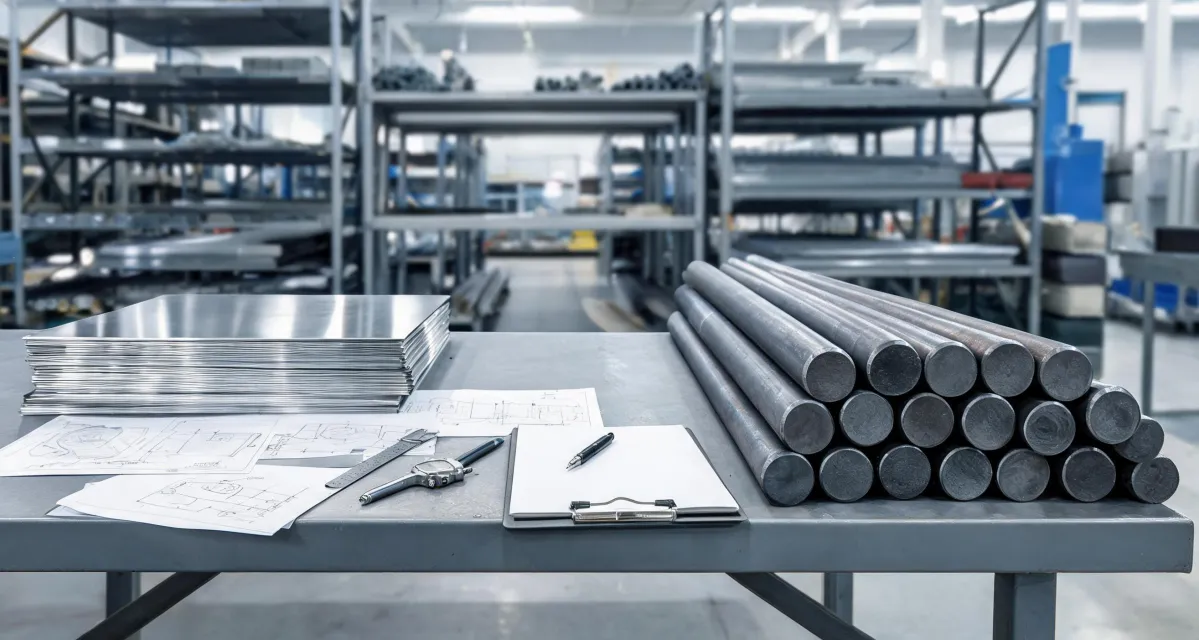
You have three quotes for replacing a load-bearing steel beam after an insurance repair notice. One vendor lists 'structural steel' without a grade, another provides ASTM-certified documentation at a higher price, and a third offers a mill test report. The adjuster wants proof of compliance within 30 days, and your budget is tight. The decision is not about price—it is about which material will survive a risk review.
The Hidden Cost of Picking a Cheap Steel Supplier
You have just received the repair notice in the morning, and by afternoon three quotes are in your inbox. The low bidder, undercutting the others by 18%, writes only 'structural steel' on the proposal, with no alloy grade, no heat number, and no certificate. The second supplier, 20% higher, attaches a full ASTM-compliant data sheet that names the grade and lists mechanical property limits. The third falls in between, offering a mill test report from the factory but no independent verification. Your claim adjuster has set a 30-day deadline for material documentation, and your contractor is already asking which beam to order. The cheapest option would free up cash for other repairs, but it would also leave the insurer without the information needed to classify the risk. As the deadline ticks, the trade-off becomes concrete: save money now or secure your claim later. Which quote do you sign?
Material property differences are not abstract engineering trivia; they feed directly into how an insurer prices risk and settles claims. The Technical Manual for Custom Rolled Aluminum Coil notes that some aluminum alloys can match or even exceed the strength of common construction steel, while retaining toughness at low temperatures and resisting atmospheric and marine corrosion. That comparison matters because it shows that 'structural' is not a single property: strength, corrosion resistance, and toughness vary by alloy and temper. If a supplier cannot specify the grade of your steel beam, the insurer cannot predict how that beam will behave under a storm load, a seismic event, or decades of humidity. An unverified grade leaves the carrier to assume the worst-case failure mode, which typically means a higher premium, a longer claims review, or an outright denial if the material is later found non-compliant. The hidden cost of a cheap quote, therefore, is not the price difference—it is the probability that your coverage does not pay out when the structure actually fails.
What Material Grades Tell an Insurer
What kind of material upgrade actually changes durability in a way an underwriter cares about? Consider the study 'Enhancing Corrosion Resistance of Stainless Steel 304 Using Laser Surface Treatment,' published in the Eurasian Chemico-Technological Journal. The research subjected AISI 304 stainless steel to laser treatment under different power densities, scan speeds, and shielding gases, and found that the surface modification measurably improved corrosion resistance. The implication for structural steel is direct: the same base grade can perform very differently depending on manufacturing treatment and finishing. A beam that is merely 'steel' tells the insurer nothing about whether it will resist pitting in a coastal garage or stress corrosion cracking in a chlorinated environment. That is why grade designations matter—they encode mechanical limits such as tensile strength and yield point, and treatment codes like H14 or T6 signal how the material was worked. When your supplier's quote omits these details, you are asking the insurer to cover a component with unknown properties. Would a carrier write that coverage at a standard rate? Most will not.
The 5052 vs 6061 vs 7075 comparison illustrates why grade selection changes mechanical and environmental performance. 5052 offers excellent corrosion resistance and higher strength than 3003, making it a common choice for marine environments and fuel tanks. 6061 is a strong structural alloy with good machinability, widely used in CNC and aerospace frames. 7075 trades some corrosion resistance for very high strength, suited for defense and high-load applications. These three aluminum grades come from the same base material family, yet they are not interchangeable in a design, and the same logic applies to structural steel. A general-purpose structural steel may deliver moderate strength and weldability for typical building frames; a higher-yield grade provides better performance for seismic-resistant moment frames; a weathering grade forms a protective patina for outdoor exposures. When a supplier writes only 'structural steel' on the quote, they are not giving you a material—they are giving you a black box. That black box forces underwriters to use conservative assumptions, and conservative assumptions carry a price. The insurer cannot evaluate a black box. It will assume the lowest-cost interpretation, which usually translates into a higher risk classification, a larger premium, or a claim left unpaid after a failure.
Three Verification Moves Before You Sign
How do you turn that material knowledge into a reliable supplier check? Build a three-step verification route before you sign anything. First, demand a grade certificate—a mill test report or certified data sheet that names the exact alloy and temper, with chemical composition and mechanical property limits. Second, ask for third-party test reports from an independent laboratory, not just the manufacturer's own numbers. Third, verify that the specified grade aligns with your local building code and the insurance policy's engineering requirements. Price is a lagging indicator; it tells you what the market charges today, but it says nothing about whether the beam will carry the load your house demands in twenty years. The cheapest quote without documentation is not a bargain—it is a gamble in which you bet your claim and your home's structural integrity against the adjuster's scrutiny. Are you willing to place that bet?
To see what a compliant grade certificate looks like, examine the technical data sheet for Alfrex flat sheet, alloy 3003-H14, which states 'ASTM B209 COMPLIANCE' at the top. The sheet lists standard thickness 0.040 in (1.0 mm), standard widths 48.0 in (1,220 mm), custom width range 31.5–62.0 in (800–1600 mm), and production tolerances for width, length, and thickness. It then breaks down chemical composition against the ASTM B209 limits: aluminum remainder 97.75%, copper 0.05–0.2% with a result of 0.17%, iron 0.0–0.7% with 0.56%, manganese 1.0–1.5% with 1.19%, and silicon 0.0–0.6% with 0.18%. It also gives mechanical property limits, tensile strength minimum 20 ksi, and other values. That is the level of specificity an insurer's engineering model expects. A certificate that names the standard and reports measured values is not paperwork for its own sake—it is the bridge between a material's real behavior and the risk model that prices your coverage. If a supplier cannot produce a similar document for your structural steel, treat that as a red flag.
Matching Material to Your Home's Environment
Not every home needs the same material priority, and that is where the framework becomes situational. Compare a coastal home and a home in a seismic zone. The 5052 grade, with its excellent corrosion resistance, is favored for marine environments because salt air attacks unprotected metals; 7075, with its very high strength, suits high-load structural roles but sacrifices some corrosion performance. For structural steel in a coastal home, you might prioritize a weathering steel that develops a stable oxide layer, or a hot-dip galvanized beam to resist chloride attack. In a seismic zone, the priority shifts to strength and toughness: a high-yield grade with better ductility allows the frame to absorb energy without brittle fracture. Choosing the wrong priority can be catastrophic: a coastal beam that corrodes silently loses its load capacity, while a seismic beam that lacks ductility can snap during an earthquake. The same base material family splits into different preferred grades because the environment changes which property matters most. A generic quote that does not state the grade forces you to guess whether you are buying marine-grade protection or earthquake-grade strength—and the guess can cost you the difference between a standing house and a denied claim. So which one does your home need?
The idea that each environment has a 'best-fit' specification is not just a metaphor; it is how materials engineers actually work. The ASTM B505 standard for bronze alloys lists distinct alloys for distinct jobs: C83600 leaded gunmetal offers excellent machinability and good pressure tightness, C86300 manganese bronze provides exceptional strength, C86500 good strength with reasonable machinability, and C90700 phosphor bronze high strength with good corrosion resistance. Each designation encodes a different balance of properties, and a manufacturer would not substitute one for another without a design review. The same principle governs structural steel. If a supplier responds to your request for a load-bearing beam with a single undifferentiated price and a promise that 'it will work,' they are bypassing the entire logic of material selection. Ask them to name the grade, cite the standard, and explain how that grade matches your environment. A supplier who cannot do that is not selling engineering—they are selling uncertainty, and the insurer will price that uncertainty into your premium.
A Reusable Rule for Choosing a Supplier
So here is the reusable rule: If an insurance repair requires structural steel, choose the supplier that provides a certified grade matching local environmental stress, and verify against policy documents—no certification, no deal. That rule condenses the entire framework into one action because it forces every other consideration to surface. The certified grade tells you the material's strength and corrosion limits; the certification gives the insurer a predictable input for its risk model; the policy alignment ensures the documentation matches what the adjuster will actually accept. When you apply that rule, the decision becomes mechanical: a quote without a certified grade is disqualified, regardless of price. A quote with the right grade and documentation moves to the final comparison. This is not about being paranoid; it is about aligning incentives. The supplier who invests in testing and traceability is the one whose material will survive a claim review—and that survival is the outcome you are paying for when you choose certification over a discount.
The rule has boundary conditions. A historical building with non-standard spans may require custom fabrication and engineering sign-off, where a standard certified grade from a catalog does not apply. An unusually long beam or a high-load transfer girder in a commercial-style home may exceed the property limits of common grades, forcing a specialty alloy or a built-up section. In those cases, the rule adjusts: still demand a certified grade, but accept that the supplier must provide the engineering rationale for the chosen material and the insurer may require additional structural review. The documentation you collect—the grade certificate, third-party test report, and policy correspondence—should be filed alongside your home insurance records, because a future claim or a policy renewal may demand the same proof. Keep that file intact, and the next time a repair or a premium re-rating comes up, you will not be starting from scratch.
The beam you install this month will still be standing when the next policy renews, and the certificate you file today is the evidence that keeps your claim alive. The rule is simple: without certification, there is no deal. Let that be the last line of your decision process, not the first thing you forget when a low price appears.
Ingrid Solberg
Ingrid Solberg is an independent carbon and structural steel analyst covering steel plate, sheet, coil, pipe, beams, rebar, and galvanized products. She applies ASTM A36/A36M and A6/A6M requirements while comparing grade chemistry, yield strength, tensile strength, elongation, dimensional tolerance, weldability, and surface condition. Her evidence-led guides help engineers, fabricators, and procurement teams select suitable steel forms, define purchase specifications, and evaluate mill or service-center offers.